ONE@Work (formerly Even)
ONE Finance, Inc.
- 4.8
- 25.60K Reviews
- 1.00M
- Downloads
- Free
- Price
Screenshots
ONE@Work (formerly Even) Pros and Cons
Pros
- User-friendly interface for easy navigation.
- Comprehensive financial management tools.
- Real-time updates on transactions.
- Customizable financial goals and alerts.
- Data encryption ensures high security.
Cons
- Limited features in free version.
- Occasional syncing issues with bank accounts.
- Requires stable internet for full functionality.
- Customer support can be slow to respond.
- Some features can be complex for new users.
 Analysis by All-app
When a finance app promises to make pay easier to manage, the first question I ask is practical: what will it actually help me do, and what should I check before relying on it? ONE@Work, formerly Even, is a free finance app from ONE Finance, Inc. Its focus is closely tied to pay and day-to-day money management, so it makes the most sense for people who want help coordinating their wages, spending, and savings rather than a broad investment platform. I’d approach it as a useful companion, not as a substitute for understanding my own pay schedule or keeping a backup plan for urgent bills.
Where users can get stuck
The most important early question is whether the app can connect your work and financial details in a way that suits your situation. Linking an account or completing an enrollment step can feel straightforward when everything matches, but small differences in account information or employment details can interrupt the process. I would take a moment to check that the information I enter is current and consistent, and read each screen before moving on rather than rushing through setup.
It also helps to separate the idea of early access to earned wages from the idea of extra income. Accessing part of pay before the usual payday changes when money is available; it does not increase what you earn. That distinction matters because it can be tempting to treat an early payment as spare cash, then find the next regular pay amount feels tighter. I’d use this option for a specific timing problem, not as a routine way to stretch a budget that is already short.
ONE@Work has an average rating of 4.8 from around 78,000 ratings, and it has been installed over a million times. Those figures suggest that plenty of people have tried it, but they can’t tell me whether it will fit an individual employer or account setup. The app is rated for Everyone, and its current version is 10.106.1. I’d still judge it by whether the relevant tools work for my own circumstances.
Setup checks that make the first session easier
Before starting, I’d have the details needed to identify my work and financial accounts close at hand, along with access to the email or phone I normally use for verification. If a screen asks me to confirm something, I’d avoid guessing; checking the source information first is usually faster than trying several variations. I’d also make sure the app is up to date and that my device can run it. The app’s minimum operating system is 7.0, so an older device may need an OS check before setup.
Once inside, I’d take a short orientation lap rather than trying every money tool at once. First, I’d look for the information connected to pay; next, I’d review any spending or savings controls; then I’d decide what I actually want to use. This order helps me understand what the app is showing before I make a plan around it. A budgeting view is only useful if I can recognize the transactions and categories, so I would treat the first review as a chance to spot anything that needs attention.
A practical habit is to compare the app’s pay-related information with the records I already rely on, such as a pay statement or my usual account activity. That does not mean expecting every screen to explain every payroll detail. It means using a familiar reference point before making a decision based on a balance or timing estimate. For anything that affects a bill due date, I’d plan around the date I can verify rather than assume that an early-pay option will always solve the timing.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Recovering a workflow without making a mess
If setup stalls, I’d resist repeatedly submitting the same information. I’d first check for a simple cause: a typo, an outdated app, a weak connection, or a verification message that has not arrived where expected. Then I’d close and reopen the app and try again once the connection is stable. If the same issue continues, pausing and using the app’s available help route is more sensible than creating duplicate accounts or changing correct details just to get past a screen.
The same careful approach applies if a transaction or spending category looks unfamiliar. I’d compare it with my bank activity and make a note of the date and amount before deciding what happened. A display that seems confusing is not, by itself, proof that the underlying transaction is wrong. Keeping a small record of what I checked makes it easier to explain the problem if I need assistance, and avoids making the same changes repeatedly without knowing whether they helped.
For saving goals, I’d start with an amount that would not put a regular bill at risk. Automatic saving can be encouraging, but a goal is not helpful if its schedule leaves too little room for essentials. I’d review the plan after a normal pay cycle and adjust it if the amount feels uncomfortable. That small trial is a better test than setting an ambitious target because a progress bar looks motivating.
When the app may not be the cause
Pay timing can depend on information and processes outside an app. If a paycheck is delayed or an expected amount differs from what I anticipated, I would check the relevant payroll or account records before assuming the app caused it. Likewise, an employer-specific enrollment issue may need attention from the appropriate workplace contact. Keeping those possibilities in mind prevents a frustrating cycle of reinstalling an app when the underlying question belongs elsewhere.
There is also a broader budgeting limit to keep in view. Tracking spending can reveal patterns, but it cannot make an irregular income predictable or remove a bill that is larger than the available money. I find these tools most useful when I pair them with a simple plan: list essentials first, identify upcoming due dates, and decide what can safely go toward a savings goal. If my finances require detailed debt planning, tax guidance, or investment advice, I’d look for a specialist resource rather than expect a pay-focused app to cover everything.
Who is likely to get the most from it?
I can see ONE@Work suiting someone who wants to keep pay timing and everyday money decisions in view, especially if they are trying to understand where smaller purchases accumulate. It may also appeal to a person who finds saving difficult and prefers a concrete goal to a vague intention to “save more.” The app’s finance focus is useful when the main question is how to manage the next pay period, not how to build a complex long-term portfolio.
On the other hand, I would skip it if I wanted a general-purpose banking replacement, a detailed investment dashboard, or a budgeting system built around extensive custom reports. It is also not the right fix for a recurring gap between income and essential expenses: getting access to wages earlier may shift the squeeze rather than solve it. Someone who already has a budgeting routine that works may find another app creates extra checking without adding much value.
How it fits beside familiar alternatives
Compared with a basic banking app, ONE@Work is more specifically oriented toward pay and related money-management tasks. A bank app is usually the natural place to confirm transactions and account balances, while a standalone budget tracker may offer a different style of spending analysis. I would not assume one can replace the others in every situation. Instead, I’d use the bank as the reference for account activity and turn to ONE@Work when its pay-focused tools address a need I actually have.
That division can be helpful in an everyday scenario. Imagine a bill is due before the next regular payday and an unexpected expense has already used part of the week’s budget. I’d check the bill date and my available money first, then see whether early access to earned pay could bridge that specific gap. Afterward, I’d look at the next pay period’s essentials before deciding whether to use the option again. This keeps the feature tied to a short-term need rather than turning it into an invisible part of every month’s spending.
Putting the tools to work
Have you ever felt like your paycheck disappears the moment it hits your account? I know I have! That's where ONE@Work (formerly Even) comes in. This nifty little app promises to help you take control of your financial life, and boy, does it deliver!
Getting Started with ONE@Work
First off, let me say that setting up ONE@Work is as easy as pie. The app is available on both Android and iOS, so no one gets left out. Once you've downloaded it, the registration process is a breeze. You'll need to link your bank account, but don’t worry, the app uses bank-level security to keep your info safe. Right off the bat, I was impressed with how user-friendly the interface is. It’s clean, intuitive, and doesn’t bombard you with information overload.
A Deep Dive into the Features
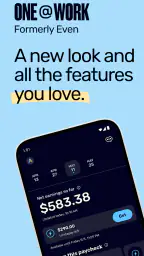
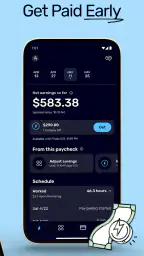
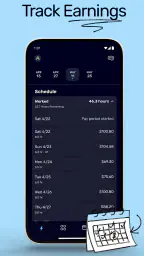
Now, onto the good stuff. ONE@Work is all about helping you manage your money smarter. One of its standout features is the ability to access your earned wages before payday. Yes, you heard that right! Instead of waiting for payday, you can get a portion of your earnings when you need them. This feature can be a lifesaver when unexpected expenses pop up. Trust me, it’s like having a financial safety net at your fingertips.
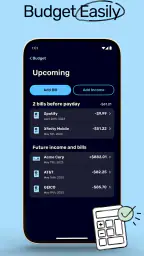
Besides that, the app offers a budgeting tool that tracks your spending and helps you plan for the future. It categorizes your expenses, so you can see exactly where your money is going. I found this feature particularly eye-opening. It’s amazing how those little purchases add up!
Saving Made Simple
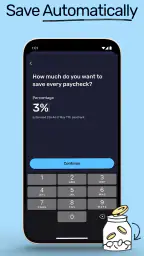
Another feature that I absolutely love is the automatic savings plan. You can set up goals, and the app will help you stash away money toward them. It's a set-it-and-forget-it kind of deal, perfect for folks who struggle with saving (like me). Plus, seeing your progress bar inch closer to your goal is incredibly satisfying.
My Personal Take
Overall, I have to say that ONE@Work is a game-changer in financial management apps. The early wage access is a breath of fresh air, and the budgeting tools are practical and easy to use. It feels like having a personal financial advisor in your pocket. While it might not replace a full-fledged financial planner, it certainly gives you the tools to make smarter decisions with your money.
If you're someone who wants to get a better handle on your finances or just needs a little extra help making ends meet, I can’t recommend this app enough. Give it a try, and you might just find yourself looking forward to managing your money (if that’s even possible!).
My practical verdict
For me, the strongest reason to try this app is the combination of pay awareness with everyday budgeting and goal-based saving. It can make the next decision feel more concrete: whether to use early wage access for a genuine timing pinch, where spending is drifting, or what amount can be set aside without jeopardizing essentials. The main trade-off is that convenience can encourage reliance on earlier access instead of making a longer-term plan, so I’d keep that feature occasional and deliberate.
ONE@Work is free and has been available since September 6, 2016. It is a finance app rather than a full financial-planning service, and that distinction shapes my recommendation. If you want a practical way to connect pay-related decisions with spending and savings habits, it is worth considering. If you need advanced planning or want every financial task handled in one place, a bank’s own tools or a dedicated budgeting service may be a better match. I’d start with one clear goal, verify the details that matter to my next pay period, and keep using it only if it makes those decisions easier.
Frequently Asked Questions
What is ONE@Work and how does it benefit employees?
ONE@Work, formerly known as Even, is a financial wellness platform designed to help employees manage their finances more effectively. It offers features such as budgeting tools, savings accounts, and paycheck advances, which can assist employees in achieving financial stability and reducing stress related to financial management.
How can I access ONE@Work and is it secure?
Employees can access ONE@Work through their employer if the service is offered as part of the employee benefits package. The app ensures user data security by employing encryption protocols and following industry standards to protect sensitive financial information. Users can feel confident about the safety of their personal data while using the app.
What are the costs associated with using ONE@Work?
The cost of using ONE@Work depends on the arrangement between the employer and the service provider. Usually, employers offer it as a free benefit to employees. However, some features, like paycheck advances, might incur small fees, which are generally lower than traditional payday loans or overdraft fees.
Can ONE@Work help me with emergency expenses?
Yes, ONE@Work is designed to assist employees in managing unexpected expenses by providing access to earned wages before payday. This feature, known as paycheck advance, allows users to cover emergency costs without resorting to high-interest loans or credit cards, thus promoting financial health and avoiding additional debt.
Is ONE@Work suitable for all employees and financial situations?
ONE@Work caters to a wide range of financial situations and is particularly beneficial for employees who need assistance with budgeting and financial planning. However, it may not be suitable for everyone, especially those who prefer managing finances independently or have complex financial needs that require more personalized financial services.